Global Markets Plunge Due to US Tariffs; Dow Jones Drops 1400 Points. Sharekhan Maintains 'BUY' Rating on Power Grid with ₹350 Target, Indicating 17% Upside Potential.
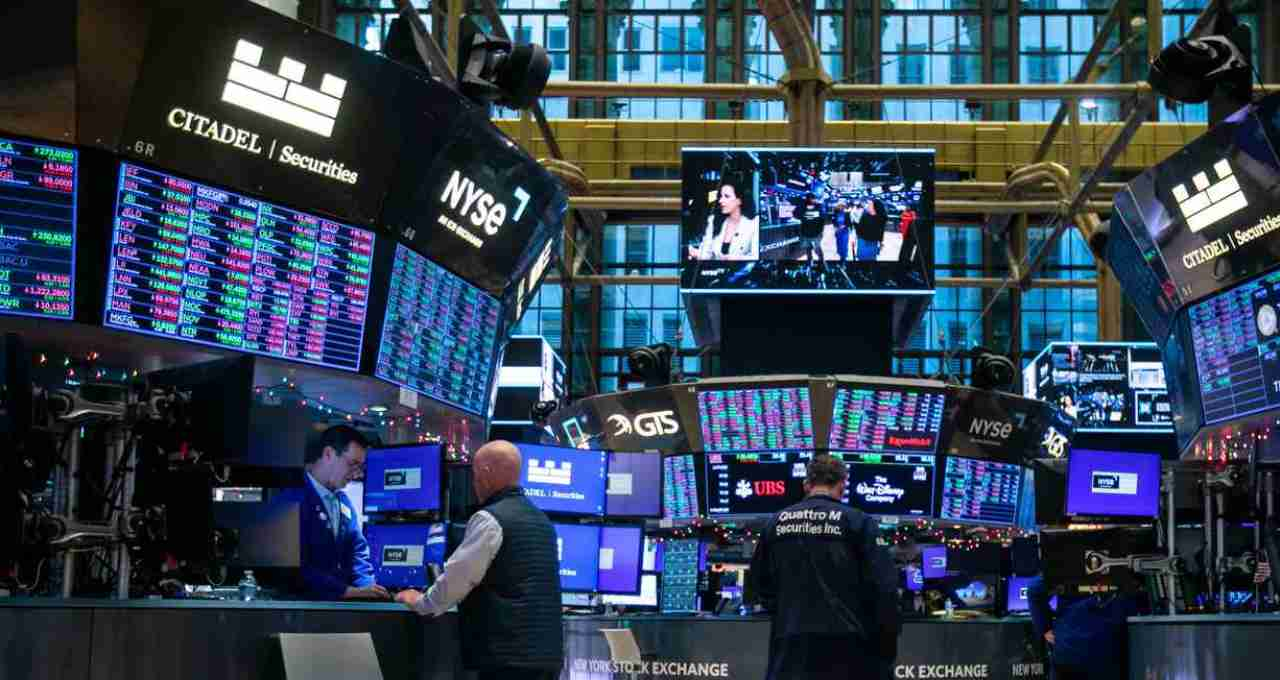
Power PSU Stock: Following the imposition of new tariffs by US President Donald Trump, global stock markets, including India's, witnessed a significant decline. The Dow Jones Industrial Average in the US market plummeted 1,400.87 points (3.32%), closing at 40,824.45. The S&P 500 experienced a drop of 232.04 points (4.09%), resulting in a $2.5 trillion loss for investors. The Indian market also felt the impact, with the Nifty-50 and Sensex experiencing a decline of over half a percent in early trading.
Sharekhan Bullish on Power Grid, ₹350 Target Price
Despite the weak market sentiment, Mirae Asset Sharekhan, a brokerage firm, recommended investment in b power sector companies. Sharekhan assigned a 'BUY' rating to Power Grid Corporation of India (PGCIL) with a target price of ₹350, suggesting a potential upside of 17%. The stock is currently trading at ₹299 on the BSE.
Power Grid Corporation of India
Power Grid Corporation of India Limited is a central public sector undertaking (PSU) under the Ministry of Power, Government of India. Headquartered in Gurugram, the company transmits approximately 50% of India's total electricity production through its transmission network. It possesses numerous long-term projects, bolstering its growth prospects.
Stock Performance Over the Past Year?
52-Week High: ₹366.20
52-Week Low: ₹247.50
16.91% increase in one month
6.06% decrease in three months
12.34% decrease in six months
6.99% increase in one year. The company's market cap is ₹2,76,506.95 crore. The stock is currently trading 18% below its high, but has shown improvement in the last month.
Why is the brokerage firm recommending a buy?
- A b project pipeline of ₹1,43,749 crore until the third quarter of FY2024-25.
- The potential acquisition of additional projects worth ₹1.9 lakh crore by FY2031-32.
- Total capex is expected to be around ₹3.3 lakh crore, providing stability to the company's growth.
- Projected PAT (net profit) CAGR growth of 6% during FY2024-27.
- RoE (Return on Equity) of 18% and dividend yield of approximately 3%.
- Expected P/BV valuation of 2.8x and 2.6x for FY26/FY27 respectively.
(Disclaimer: This report is for informational purposes only. Consult your financial advisor before making any investment decisions.)