Many people consider loan closure and loan settlement to be the same, but there is a significant difference between the two. In loan closure, the customer repays the full amount, which helps maintain a better credit score. Whereas in loan settlement, the bank waives a portion of the amount, which negatively impacts the credit score and can make it difficult to obtain future loans.
Loan Settlement: Often, due to financial difficulties, people are unable to fully repay loans taken from banks and opt for settlement. However, this decision can lead to difficulties in the future. In loan closure, the customer repays the entire amount including interest, whereas in settlement, the bank waives a certain amount. According to experts, settlement damages the credit score and makes it difficult to obtain future loans or credit cards. Therefore, it is important to make a thoughtful decision based on the situation.
What is Loan Closure
Loan closure means that the customer has fully repaid the entire loan taken from the bank. This includes the repayment of both interest and principal. The customer can make these payments on time through EMIs or by paying a lump sum amount to close the loan. Once the customer repays the full amount, the bank closes the loan and issues a No Objection Certificate (NOC) to the customer.
After loan closure, the customer's record is registered as good with both the bank and the credit agency. This indicates that the customer has fulfilled their financial responsibilities correctly. This is why loan closure does not have any negative impact on your credit score. Rather, it can further improve the score because you have fulfilled your liabilities on time.
When Does Loan Settlement Occur
Loan settlement occurs when a customer is unable to repay the full loan amount due to some reason. For example, in situations like job loss, business losses, or sudden expenses from a major illness, an individual negotiates with the bank and settles by making a partial payment. This is referred to as loan settlement.
In this situation, the bank takes a portion of the amount from the borrower and waives the rest. The bank does this only when it is convinced that recovering the full amount from the customer is no longer possible. While this process certainly offers easy relief to the customer, it also has serious consequences.
Impact on Credit Score
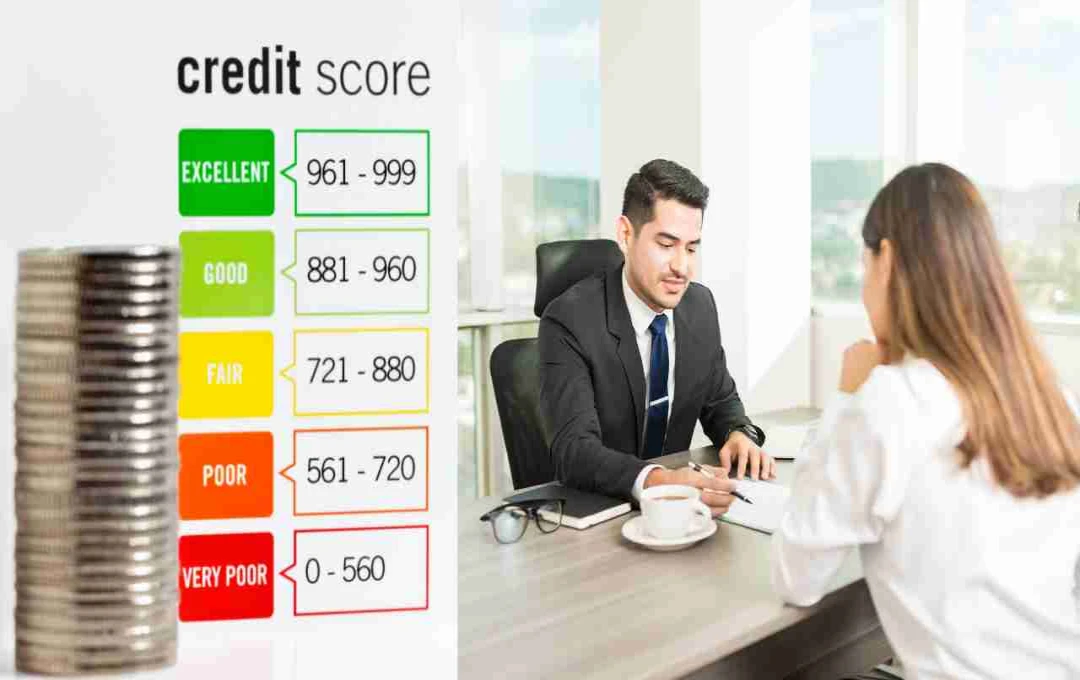
After a loan settlement, the bank sends this information to credit bureaus (CIBIL, Experian, etc.). There, the customer's record is updated with a “Settled” status. This means that the customer did not repay the full loan amount but settled by paying a portion.
This status significantly damages your credit score. Typically, it can lead to a drop of 75 to 100 points in the score. Banks or other financial institutions view such customers as high-risk. Consequently, obtaining future loans or credit cards can become quite difficult. Often, applications are even rejected.
Loan Settlement from the Bank's Perspective
For banks, loan settlement is also a last resort. When the bank apprehends that recovering the full amount from the customer is difficult, it settles the matter by accepting a partial amount. However, the bank records it as a “Loss” in its books.
After settlement, the possibility of recovery from the customer is almost eliminated. Therefore, the bank marks it as a negative point in the customer's credit profile. This is why banks and NBFCs avoid lending to such customers in the future.
What is the Difference Between Loan Closure and Settlement
Although loan closure and loan settlement may sound similar, their processes and impacts are completely different.
In loan closure, the customer closes the loan by repaying the full amount. This keeps their record good and makes it easier to obtain loans in the future.
In loan settlement, the customer does not repay the full amount but settles by paying a partial sum. This negatively impacts the credit score and reduces the chances of getting a loan next time.
When Does the Settlement Option Arise
The settlement option arises when a customer has not been paying EMIs for a long time. The bank contacts the customer after sending several notices. If the bank believes that the customer's financial situation is very poor and recovery is difficult, it offers a settlement proposal.
The customer closes the loan by paying the settlement amount, but its impact remains on their record for years.